“Private equity” has become a dirty word in my circles. I partly understand why, and partly don’t. That led me to dig deeper into how I feel about the topic. For this conversation, I’m grouping together any outside investment a Christian tech company takes, whether that’s going public (IPO), raising venture capital (VC), or selling to private equity (PE) in some form.
This is such a hot topic because, if you look at the top ten Christian tech companies, only two are still fully privately owned. At least, they haven't disclosed any outside investment. If you are privately owned, your books get to stay private. Another reason this is such an interesting topic is that the top ten Christian tech companies make an estimated $1.5 billion in annual revenue. That is a lot of tithe dollars. The reality is we all use these platforms and tools in some way at our churches and ministries. So, the challenging question for some is: why is taking money from an outsider to build more things bad? Let’s start with the bigger question before I give my answer.
Compound or slingshot
You can build something slowly, improving it consistently over a long period. Or you can speed up the process and try to reach the same result much faster. Neither approach is automatically better. But each requires different kinds of faith, risk, and patience.
When you build over time, you have room to learn. You find out more about your market, your product, and your development process. You discover which feedback matters, who not to listen to, and what people actually need. You can make small mistakes, course-correct, and keep moving.
In slingshot mode, you have less margin for error. Sometimes you have to make bigger bets on incomplete information and hope your instincts are right. One wrong feature, one bad hire, one expensive campaign, or one misread of the market can put the entire project at risk. And the faster you spend, the faster the idea has to win.
The Hollywood version
Hollywood makes this easy to see. A movie can be good and still fail financially because the economics demand too much. Studios do not keep every dollar from ticket sales, and marketing adds a massive expense on top of production. That is why a movie needs to earn about 2.5x its production budget worldwide to have a real shot at breaking even.
The Fantastic Four: First Steps reportedly cost about $200 million to make and earned roughly $522 million worldwide. That sounds enormous, but factoring in the 2.5x needed shows it barely made money. It also shows the pressure that comes with a giant budget. A movie can make more than half a billion dollars and still land near the line where it narrowly justifies the investment rather than becoming an unquestioned win. More money equals more pressure to deliver, and the bigger the win needs to be.
I first understood this when Disney released John Carter. It grossed about $284 million worldwide, but its production budget was reported in the $250–300 million range, before fully accounting for marketing and the theater share of ticket revenue. Disney reportedly took roughly a $200 million write-down. I remember watching it and thinking, “This isn’t a terrible movie.” It wasn’t a great movie either. And it for sure didn’t feel like one of the biggest failures in movie history. But that is the point: it had to be extraordinary to carry its budget. It was set up for failure from the start. The bigger the bet, the less room there is for an okay movie.
Now compare that with Godzilla Minus One. The film had a reported production budget of about $15 million and earned roughly $114 million worldwide. That is more than 7x its budget. It was made with far fewer resources, but the lower cost made success much more achievable. The pressure was still real. Nobody spends $15 million casually. At least I don’t. But once the movie crossed its production budget, the story changed quickly. The project didn't need to become a global billion-dollar franchise to be considered a win. It needed to deliver an entertaining movie at a disciplined cost. That is a very different kind of weight.
Tech has the same problem
Tech companies do this all the time, just like Hollywood. They spend huge amounts of money quickly and need a home-run product or service to survive. They do not want to build slowly. For example, Anthropic is going public soon and disclosed that it made about $4.6 billion in revenue and posted a $42 billion loss in 2025 alone. They are losing money, but you have to believe Anthropic will make money in the future, right? That is the bet with a bigger investment. They say not to worry about the billions lost today and to focus on future gains, and the market seems to agree with the Anthropic bet.
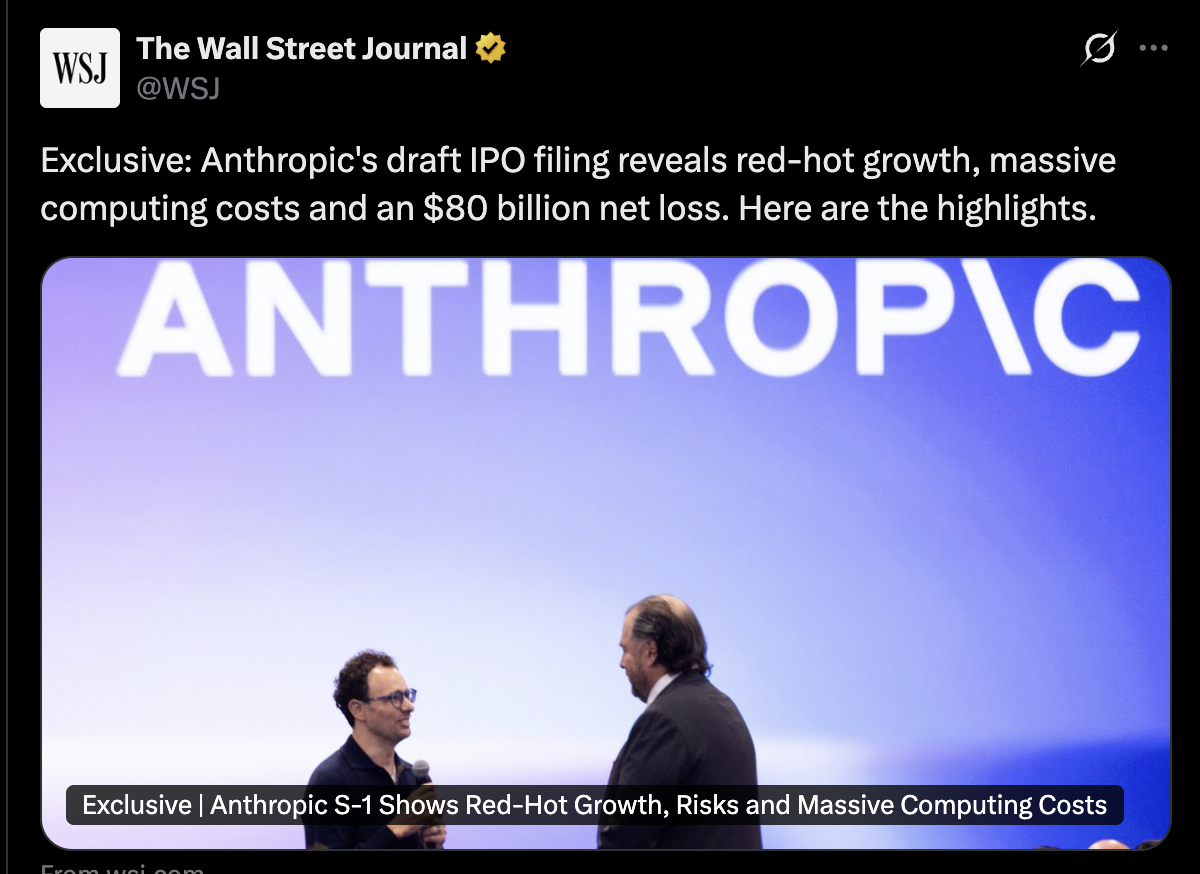
The reality is that these bigger bets require a bigger win, so they need to raise more money, take on even more debt, hire aggressively, and assume future revenue will justify the spending. They are swinging for a grand slam. They don’t want to just get on base. Sometimes this type of strategy creates an incredible company. Other times, it turns a decent business into a desperate one, like John Carter, a solid movie that got called a failure because it couldn’t live up to what it cost.
Warning: bad language. A popular clip from the HBO show Silicon Valley circulates on X a ton. The venture capitalist says, "I don't want to make a little bit of money every day; I want to make a [expletive] ton of money all at once."
What approach is better?
The slow-build approach is less glamorous, but it has real strengths. A company can improve its product using the margin and trust it earns along the way. It can grow from real customer demand rather than investor expectations. The growth may feel frustratingly slow at first, but it can compound over time. It is similar to long-term investing. The early years are unimpressive. But if you stay disciplined, much of the gain can come late in the process, after years of steady compounding. That approach is valid. It is just slower, too.
The alternative is to take a bigger swing. Raise capital. Take out a loan or bring in private equity. Sell a small portion to someone who can help scale your product or service. Outside investment usually comes not just with dollars and cents, but with expertise in scaling and expanding your offering. It’s like Mark Cuban investing in your company on an episode of Shark Tank. When he invests, you get his knowledge and network. The same applies to taking on outside investment in Christian tech companies. A mutually beneficial partnership can accelerate what might otherwise take a decade to get off the ground.
But money is never just money. It comes with expectations. When private equity or any outside investors buy a stake, controlling or not, they often expect much faster growth. Healthy, gradual growth may no longer be enough. The company is now expected to slingshot, or at least start accelerating noticeably.
That pressure can change behavior at these faith-based tech companies. Teams may start chasing sales at all costs, cutting corners, overpromising, or treating customers as numbers needed to hit a quota. A company with a strong reputation can become unrecognizable when it feels trapped by the need to grow fast enough to justify the money it took. This is why “private equity” is seen as a negative in some circles I float in. Bad stories start to circulate about the tactics they’ve used and how the service has only gotten worse since they took on outside investment.
A word for Christian tech
Christian tech faces the same tension: grow slowly or try to slingshot. Some companies are choosing to improve steadily with the profits they earn each year. That is a valid strategy. It can be slow, but it builds durability. If they keep serving people well and making meaningful improvements, the results can compound. Often, these companies get comfortable too and don’t want to build more. The original founders get rich, and why take more risk? This isn’t always the case, but it's kind of like saying, “I’m good with what I have. I don’t need more.” As a result, sometimes users don't get new features, and these companies take years to roll out anything innovative.
Other companies move much faster. They want to build more ambitious products, reach more people, and compete at a higher level. That often requires outside investment and a willingness to take larger risks. I am not against that either. I like getting bigger and better things, but sometimes these companies never deliver on that promise. The investment goes into hiring more salespeople to get more customers, not into improving the product. Oh, and usually the offering gets more expensive in the process.
The Tesla story
Tesla is an obvious example of a company that chose acceleration. It could not pursue a world-changing electric-vehicle mission by growing only as fast as its existing cash flow allowed. Going public gave it access to more capital, but it also brought a new level of scrutiny and expectation. The company accepted more pressure because it wanted the possibility of a much larger outcome. Christian tech companies are not Tesla. I know that. But I respect Christian tech companies that want to compete, build excellent things, and take meaningful swings.
I had this conversation with a founder who built a popular Christian tech service and was wrestling with this exact decision. I didn’t know it, but he was in talks with one of the top ten companies about being acquired. We didn’t know each other well, but we started discussing the pros and cons of being swallowed up by a huge company. I said that I didn’t see it as black or white, but more as what excited him about his product roadmap. He could keep majority ownership and build it out over the next few years. Or, he could immediately get a larger user base, build more integrations into his ecosystem to improve his product for his existing customers, and of course get a good payout in the process. Then, a few years later, when the golden handcuffs come off, do it again with a new offering and build something else cool for the kingdom. I saw that as a win-win either way. He ended up being acquired, not because of my thoughts, and I think it was a wise move. I would have done the same thing.
My hope for the faith tech space
I believe we need more money flowing into Christian tech. We need more ambitious products, platforms, and services. We need people willing to build things that are actually useful, beautiful, and technically excellent. At the same time, more money brings new pressures to speed up timelines, which can become dangerous for companies. This is especially true when you're burning cash and not growing quickly enough.
Some of these Christian tech companies may have been gutted of all of their Christianity. Some I know are trying to rebuild trust after damaging their reputation. I felt there was a bit of an equity gold rush right before COVID, and that whirlwind created unrealistic expectations as people moved back into buildings after the pandemic settled. When the easy gold was gone, some outside investors put extreme pressure on these companies to keep digging, but it was already over for them.
New companies are just now taking their moonshot, which is exciting for anyone always looking for innovative things. Other companies may be moving too slowly and risk becoming irrelevant. They are stable, but they innovate at a turtle’s pace. They rely on modest returns and established trust while the world around them changes faster than they do. The tortoise may have beaten the hare, but that fable doesn’t hold up in tech.
I personally wish slower-moving Christian tech companies would take more risk, whatever that means for them. They don’t need to go for the fences, but they also shouldn’t get too comfortable with their moat. For example, you can take outside investment while keeping control of the business to launch more offerings for your customers. But it is easy for me to say that. I am not responsible for the customers, the product/service, or liable for the consequences of a bad deal.
Closing thoughts
I think we need billionaires, millionaires, and those startup vibecoders building in Christian tech. When everyone builds together in the space, it pushes everyone forward. I don’t think Elon Musk is some evil character for taking his company public, and I don’t feel that way about the top ten Christian tech companies that take outside investment. I respect people like Elon and Mark Zuckerberg for taking big risks, even when they are crazy rich. They are builders who want to keep building. I want to see more Christian tech companies take big swings. The tech the church needs will cost a lot of money to build, so let’s stop dismissing outside capital and throwing mud at people for wanting to do more. Let's not get all worked up because someone will profit from it. Instead, let’s ask and demand that these companies build more cool things that win us over. The price should be worth what it does for us.
Also, it's okay to hold these companies accountable. If they do something wrong, we need to call them out. That pressure needs to be on them. It’s part of the gig. If you collect from the tithe, then a little Ananias and Sapphira heat isn’t bad. The church can hold them to a higher bar compared to secular tech companies. I think most are game to be held to this higher standard, too.
If you own a Christian tech company, thank you for doing what you do. I’m praying for wisdom as you navigate the complexity of staying competitive in this ultra-competitive space. Praying as you navigate when to swing and when to chill in the dugout. This post has too many baseball references.
So, compound or slingshot? There isn’t one right answer. If a company takes the money, watch where it goes. If a company builds slowly, make sure it’s still building. And if you’re a church paying for their product/service, you get a vote either way. Ask the hard questions and keep paying the ones that keep earning it. I’m not scared of private equity, but I’m also not naive about what it can do to a company that doesn’t keep it in check. Okay, now let’s go build cool things for Jesus.